Both well known companies of same sector viz. Adhunik Corporation Ltd & Jai Balaji Industries Ltd. are Kolkata based and made remarkable performance right from there incorporation.
They had a bright future if they would be success to mature there proposal of treatment of Fines.
In
Adhunik Corporation & Jai Balaji has joined hands to introduce treatment of those fine particles thereby making utilization of so called waste and making huge gains , it would help to boost up there gains in the coming financial years with a promising future ahead.
Though the entire plan is yet under purview and is likely to mature.Though the future is always uncertain so it could not be guaranteed but if could mature the price of the stock will soar. It wouldn't be a bad idea to have some holdings of either of the stocks in our portfolio.As the stock has seen good correction in the market's cyclical bear phase so the price of the stock is also justified.
WHY JAI BALAJI & ADHUNIK ?
GOLD WILL GLOW SOON

Being a professional advisor on Finance and wealth I do highly recommend to accumulate Gold as the best investment opportunity.
Though due to recent RBI credit policy the interest rate of fixed deposit has hiked to a remarkable point but its limitation is to the extent that fixed deposit is possible for available funds in the income tax file but the hard cash , which is also called as black money in collaqual language could be safely investment without hassle with expectation of good return in short , medium , long period.The main plus point is that Gold is as good as cash which is encashable at any point of the world.
Gold & Silver price is going to soar and have great future so this is safe and highest return yielding investment for both white and black money.
In
In foreign countries a plan called "GAP" has been executed whereby a recurring type account with a passbook is opened such that every month you deposit a fix amount of money which is used to buy gold on a particular date irrespective of the price on that date. You get the balance of the gold accumulated in your account at any day. If you wish to take gold on certain date you may take the gold and if you want to encash the gold you may opt for cash of the value of the gold as on that date.
This system not only help to invest in gold in easy installment which is not practically possible but also give the benefit of liquidity and safety. Buying Physical gold may arise question of safety so this system is fool proof but not yet introduced in
SHORT TERM CAPITAL GAIN TAX :NIL , HOW?
Most of the trader are facing a giant unsolved problem of paying a huge amount of tax as short term capital gain.
Capital gain tax arise on any gain made on buy & sell of stocks , property etc. If the transaction of buy & sll is done within a period of 12 months it is titled as short term capital gain , while transaction for more than 12 months is long term capital gain.
As per last union budget tax on long term capital gain is nil while short term capital gain tax is 10%.
Most of the day traders , short term traders when assess there balance sheet at end of the financial year , a large part of there earning goes in payment of tax on short term capital gain.
If you are stuck in the same problem , you can solve by not paying a single penny as tax . The procedure disclosed is cent percent legal and is called tax planning but not tax evasion.
FOR PROPERTY SECTION
If the short term profit earned on property is reinvested in other property within 6 months then no tax is payable for that financial year for short term gain.
FOR STOCK TRANSACTION
The amount of profit earned as short term capital gain on stock is reinvested in NABARD BOND of Govt. of India for 3 year lock in period with fix interest rate (1% less then normal fixed deposit rate) will tax free. and also after 3 years the total maturity amount from NABARD BOND is also have no tax laiblity.
ELLIOT WAVE ANALYSIS FOR THE WEEK ENDING ON 15/08/2008
The very first upside task for the Index would obviously be taking over the last week’s high of 15422. Remember, this was the level close to previous gap-down area of 15259-390, where previous impulse had ended. Once the Index is able to sustain above 15422, we can consider 15600-650 as the next crucial target/resistance, which is nothing but 50-61.8% level to last Dark Cloud Cover pattern I have been marking for a long time. Beyond this, the next crucial resistance is at around 15750, which is the 61.8% correction level to channeled fall from 17735 to 12514. And the maximum level would be 16172, the 70% correction level to the same fall.
Remember, the fall from 17735 to 12514 was a channeled Complex Corrective fall. Such a pattern usually gets corrected to the extent of 60% to 70%. All our upside targets, explained above, are close to this pattern implication. Time-wise, since the fall from 17735 to 12514 had taken 10 weeks (in what was labeled as the “a” leg of 2nd corrective), the current corrective phase (“b” leg) should form over 10 weeks or preferably more. So far, the rally, beginning 12514, has consumed only three weeks. We may, therefore, see Sensex moving sideways once our upper targets area met, in order to consume the necessary time of more than 10 weeks.
ELLIOT WAVE ANALYSIS FOR (18/08/08 TO 22/08/08)
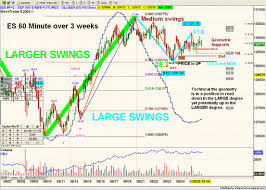
During the week, Index initially moved higher by 412 points to touch 15579.Sensex expectedly faltered and lost 893 points by the end of the week. The net close was lower by 443 points or 3%.
The hesitation at target levels was shown by the break of 20-day long Green trend line I’ve shown on the Daily chart. Also, two gap-up actions (on 6thth Aug) closer to our target area, were completely covered.
The hesitation confirmed when the last segment of rally (from last Friday’s low of 14888 to Tuesday’s high of 15579) was completely retraced in faster time. On its weekly chart, Sensex formed a bearish Dark Cloud Cover pattern.
Weakness below 14175, continuing after 2 days of trading, would bring the Diametric assumptions in play. Diametric assumption, as I argued, stemmed from the weakness in the structure, as the rally from 13727 to 15579 had taken 161.8% time to achieve 75% magnitude compared with the previous rally from 12514 to 15130. A drop below 14175 would confirm further weakness in the structure by making the current drop (from last week’s high of 15579) bigger than the previous fall from 15130 to 13727.
Therefore, choice of structure for the rally, whether it’s a Zigzag or a Diametric, will depend on whether the Sensex holds around 14100 or not. Short term consequences will follow accordingly. Zigzag will be bullish, as its “c” leg will move higher. Diametric will be bearish as “d” leg can drop to 13727 or even lower.
Time-wise, I had argued that since the fall from 17735 to 12514 (in what was labeled as the “a” leg of 2nd corrective) had consumed 10 weeks, the current corrective phase (“b” of 2nd) should form over 10 weeks or preferably more.
If the “b” of 2nd (or what I called as bear market rally post-12514) consumes lesser time than 10 weeks, then the larger structure within the 2nd
Also by rules, the Complex Corrective fall from 17054 to 12514 which was actually a Triple Zigzag, can occur only as the largest leg of Triangle (or Terminal). This has already suggested Extracting Triangle into 2nd wave position after “x”. and 11 corrective can also go into the realms of Extracting Triangle or Diametric, which are the only alternative configurations which allows “b” legs to consume lesser time.
RIGHTS OF INVSTORS
1. To get all material information declared for the Investors’ by the Company.
2. Prompt Services from the Company such as transfers, Sub-divisions and consolidation of holdings in the Company.
3. Equity holders have a right to subscribe to further issue of Capital by the Company.
4. Brokerage not to exceed 2.5 per cent of the Contract Price.
5. Receipt of the Contract note from the broker in the specified format showing transaction price and brokerage separately.
6. Investors can expect delivery of shares purchased/value of shares sold within 2 days after the pay-out day.
7. Access to the Exchange arbitration facilities in case of dispute with brokers. Contact : The Investors’ Service Cell, The Stock Exchange, 1st Floor , Rotunda Bldg, Mumbai – 400 001
8. For complaint against listed Companies/brokers contact: The Investors’ Service Cell, The Stock Exchange,1st Floor, Rotunda Bldg, Mumbai –400 001.
INVESTORS HELP CENTRE
- Refund order/Allotment Advice
- Non Receipt of dividend
- Non- Receipt of Share Certificates after transfer
- Debentures related issues
- Non- Receipt of letter of offer for Rights
- Collective Investment Schemes.
- Mutual Fund Portfolio Managers, Custodians
- Brokers, DP’S Merchant Bankers, Registrars and Transfer Agents and other intermediaries
All the complaints are mandatory to be properly typed preferably on the format given by SEBI, which is annexed as an Annexure to the OIAE Division of SEBI at Mumbai or Regional Offices
Addresses Of SEBI Offices
SEBI Head Office: Mittal Court, ‘A’ Wing 1 st Floor 224, Nariman Point, Mumbai-400 021.Tel Nos: 022-22880962-70, 22850451-56 Email: iggc@sebi.gov.in
SEBI OIAE : 4 th Floor, Exchange Plaza, ‘G’ Block, Bandra Kurla Complex, Bandra (E) Mumbai-400 051. Tel Nos: 022-26598510-13, Email: iggc@sebi.gov.in
SEBI North Regional Office: Block No 1 Rajendra Bhawan,
SEBI Eastern Regional Office: L&T Chambers, 3 rd Floor 16,
SEBI Southern Regional Office: 3 rd Floor, D’ Monte Bldg,No 32, D’Monte Colony,TTK Road Alwarpet,Chennai-600 018 Tel: 044-24995676/5525/7385 Email: sebisro@sebi.gov.in
These are some of concerned regulatory authorities to be addressed
THE STOCK EXCHANGE: At the investor Information Centre of all the recognized stock exchanges
- Related to securities traded/listed with the exchange
- Trades affected on the exchange w.r.t. the companies listed on it or by the members of the stock exchange.
DEPARTMENT OF COMPANY AFFAIRS/REGISTRAR OF COMPANIES (ROC)
- Against unlisted companies
- For non-receipt of annual report,AGM notice
- Fixed deposit in manufacturing companies
- Forfeiture of shares
RESERVE BANK OF
- Fixed Deposits in Bank
- Fixed Deposits in Non Banking Finance Companies
The nature of complaints received by the Exchange can be broadly classified into the following categories:
- Non-receipt of delivery of shares/ Non removal of objection/Non-receipt of sale proceeds of shares/ Non-receipt of dividend/ Non-receipt of Rights, Bonus shares
- Disputes regarding Rate Difference
- Disputes relating to non-settlement of Accounts
- Miscellaneous Items
The complaints are forwarded to the concerned members to reply /settle the complaints within 7days from the receipt of the letter. If no reply is received or reply received is not satisfactory, the matter is placed before the IGRC (Investor’s Grievance Redressal Committee) headed by Retd. High court Judge. IGRC is constituted by the Governing Board to resolve the Complaints of non-members against Members through the process of reconciliation. The parties are heard and the matter is tried to be solved amicably or it is referred for Arbitration under the Rules, Bye-laws & Regulations of the Exchange.
RBI BONDS DETAILS
It could be issued to any of the following category:
i. An individual, not being a Non-Resident Indian -
(a) in his or her individual capacity
(b) in individual capacity on joint basis
(c) in individual capacity on anyone or survivor basis
(d) on behalf of a minor as father/mother/legal guardian
ii. Hindu Undivided Family
iii. Charitable Institution' to mean a Company registered under Section 25 of the Indian Companies Act 1956 .
iv. An institution which has obtained a Certificate of Registration as a charitable institution in accordance with law a in force [OR]
v. Any institution which has obtained a certificate from Income Tax Authority for the purposes of Section 80G of the Income Tax Act, 1961.
vi. "University" means a university established or incorporated by a Central, State or Provincial Act, and includes an institution declared under section 3 of the University Grants Commission Act, 1956 (3 of 1956), to be a university for the purposes of that Act.
=============================================================================
APPLICATION PROCESS
i. Applications for the Bonds may be made in Form ‘A’ (Annex 2) or in any other form as near as thereto stating clearly the amount and the full name and address of the applicant.
ii. Applications should be accompanied by the necessary payment in the form of cash/drafts/cheques as indicated in paragraph 6 above.
===========================================================================
INTEREST ON BONDS
Applications for the Bonds in the form of Bond Ledger Account will be received at:
i. The bond will be issued in cumulative and non-cumulative form, at the option of the investor.
ii. The Bond will bear interest at the rate of 8% per annum. Interest on non-cumulative bonds will be payable at half-yearly intervals from the date of issue in terms of paragraph 7 above. Interest on cumulative bonds will be compounded with half-yearly rests and will be payable on maturity along with the principal. In the latter case, the maturity value of the Bonds shall be Rs.1601/- (being principal and interest) for every Rs.1,000/-(Nominal). Interest to the holders opting for non-cumulative Bonds will be paid from date of issue in terms of paragraph 7 above upto 31st July/31st January, as the case may be and thereafter at half-yearly for period ending 31st July/31st January on 1st August and 1st February. Interest on Bond in the form of “Bond Ledger Account” will be paid, by cheque/warrant or through ECS by credit to bank account of the holder as per the option exercised by the investor/holder.
==============================================================================
NOMINATIONS
A sole holder or a sole surviving holder of a Bond, being an individual, may nominate in form B (Annex – 4) or as near thereto as may be, one or more persons who shall be entitled to the Bond and the payment thereon in the event of his/her death.
=============================================================================
REPAYMENTS
The Bonds shall be repayable on the expiry of 6 (Six) years from the date of issue. No interest would accrue after the maturity of the Bond
===========================================================================
RECEIVING OFFICES
Applications for the Bonds in the form of Bond Ledger Account will be received at:
i. Authorised Branches of State Bank of
============================================================================
RBI GUIDELINES FOR BANKS TO APPOINT RECOVERY AGENTS
Banks are advised to take into account the following specific aspects while engaging recovery agents:
(i) Banks should have a due diligence process in place for engagement of recovery agents, which should be so structured to cover, among others, individuals involved in the recovery process.
(ii) To ensure due notice and appropriate authorization by the banks, they should inform the borrower the details of recovery agents engaged for the purpose, while forwarding default cases to the recovery agents. The details should include their telephone numbers etc. The recovery agents should call the borrowers only from telephone numbers notified to the borrower.
(iii) Each bank should have a mechanism whereby the borrowers' grievances with regard to the recovery process can be addressed. The details of the mechanism should also be furnished to the borrower while advising the details of the recovery agent as at item (ii) above.
Methods followed by Recovery Agents
(iv) It is understood that some banks set very stiff recovery targets or offer high incentives to recovery agents. These have, in turn, induced the recovery agents to use intimidatory and questionable methods for recovery of dues. Banks are, therefore, advised to ensure that the contracts with the recovery agents do not induce adoption of uncivilized, unlawful and questionable behaviour or recovery process.
(v) A reference is invited to para 2 (v) (c) of Circular DBOD.Leg.No.BC.104/ 09.07.007 /2002-03 dated May 5, 2003 regarding Guidelines on Fair Practices Code for Lenders and para 6.3 of the Master Circular DBOD.FSD.BC.17/ 24.01.11/2007-08 dated July 2, 2007 on Credit Card Operations. In terms of these guidelines, banks were advised that in the matter of recovery of loans, (a) the lenders should not resort to undue harassment viz. persistently bothering the borrowers at odd hours, use of muscle power for recovery of loans, etc. (b) the banks should ensure that agents engaged by them for debt collection refrain from action/s that could damage the integrity and reputation of the bank (c) their agents should not resort to intimidation or harassment of any kind, either verbal or physical, against any person in their debt collection efforts, including acts intended to humiliate publicly or intrude into the privacy of the borrowers'/ credit card holders' family members, referees and friends, making threatening and anonymous calls or making false and misleading representations.
(vi) A reference is also invited to paragraph 6 of the 'Code of Bank's Commitment to Customers' (BCSBI Code) whereby banks are required to strictly abide by the codes pertaining to collection of dues.
Training for recovery Agents
(vii) In terms of
(viii) Reserve Bank has requested the Indian Banks’ Association to formulate, in consultation with Indian Institute of Banking and Finance (IIBF), a certificate course for Direct Sales Agents / Direct Marketing Agents / recovery Agents with minimum 100 hours of training. Once the above course is introduced by IIBF, banks should ensure that over a period of one year all their recovery Agents undergo the above training and obtain the certificate from the above institute. Further, the service providers engaged by banks should also employ only such personnel who have undergone the above training and obtained the certificate from the IIBF.
Taking possession of property mortgaged / hypothecated to banks
(ix) In a recent case which came up before the Honourable Supreme Court, the Honourable Court observed that we are governed by rule of law in the country and the recovery of loans or seizure of vehicles could be done only through legal means. In this connection it may be mentioned that the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 (SARFAESI Act) and the Security Interest (Enforcement) Rules, 2002 framed thereunder have laid down well defined procedures not only for enforcing security interest but also for auctioning the movable and immovable property after enforcing the security interest. It is, therefore, desirable that banks rely only on legal remedies available under the relevant statutes which allow the banks to enforce the security interest without intervention of the Courts.
(x) Where banks have incorporated a re-possession clause in the contract with the borrower and rely on such re-possession clause for enforcing their rights, they should ensure that such repossession clause is legally valid, is clearly brought to the notice of the borrower at the time of execution of the contract, and the contract contains terms and conditions regarding (a) notice period to be given to the customers before taking possession (b) the procedure which the bank would follow for taking possession of the property and (c) the procedure which the bank would follow for sale / auction of property. This is expected to ensure that there is adequate upfront transparency and the bank is effectively addressing its legal and reputation risks.
Use of forum of Lok Adalats
(xi) The Honourable Supreme Court also observed that loans, personal loans, credit card loans and housing loans with less than Rs.10 lakh can be referred to Lok Adalats. In this connection, banks' attention is invited to Circular DBOD.No.Leg.BC.21/09.06.002/2004-05 dated August 3, 2004 wherein they were advised to use the forum of Lok Adalats organized by Civil Courts for recovery of loans. Banks are advised that they should preferably use the forum of Lok Adalats for recovery of personal loans, credit card loans or housing loans with less than Rs.10 lakh as suggested by the Honourable Supreme Court.
3. Banks, as principals, are responsible for the actions of their agents. Hence, they should ensure that their agents engaged for recovery of their dues should strictly adhere to the above guidelines and instructions, including the BCSBI Code, while engaged in the process of recovery of dues.
4. Complaints received by Reserve Bank regarding violation of the above guidelines and adoption of abusive practices followed by banks’ recovery agents would be viewed seriously. Reserve Bank may consider imposing a ban on a bank from engaging recovery agents in a particular area, either jurisdictional or functional, for a limited period. In case of persistent breach of above guidelines, Reserve Bank may consider extending the period of ban or the area of ban. Similar supervisory action could be attracted when the High Courts or the Supreme Court pass strictures or impose penalties against any bank or its Directors/ Officers/ agents with regard to policy, practice and procedure related to the recovery process.
INVESTMENT RULES IN EQUITY MARKET
Not only the small investors but also institutional investor has the challenge to find the right opportunity to invest in stock market and at right time (To enter/exit). Generally investor are happy to make heavy gains during rally but with agreed doesn't book profit but on other hand when market scenario get reverse they are scared faster and sell out the holding even at loss.
In short, investing in equities can be a difficult proposition for retail investors. However, equity must form a part of every investor’s portfolio. The proportion could vary, depending on the investor’s age, monetary requirements, risk appetite, etc.
It is important to have a disciplined and systematic approach to equity investment. Set your own rules and more importantly, follow them strictly.
A long-term monetary commitment, adherence to discipline in investment and decisions based on company fundamentals are essential ingredients for successful equity investment.
Golden rules for investment
1. To be a long term investor
2. Do Your home work Regularly
3. Try to average Price at both buying and selling time
4. Diversification of portfolio
5. Always focus on fundamentals
6. Don’t sell in panic
7. Don’t take loan to invest
8. Invest regularly & gradually
9. Have targets & exit at those level strictly.